How to Apply for Wazir-e-Azam Apna Ghar Program (Ghar Ho Tu Apna): Complete Guide
Owning a home in Pakistan has become difficult for many families. Rents keep rising, and a regular bank loan often comes with installments that a middle income household cannot manage. To ease this problem, the government launched the Wazir e Azam Apna Ghar Program, Ghar Ho Tu Apna. This guide explains what the scheme is, who can apply, which documents you need and how to complete the online application.
1. What Is the Wazir e Azam Apna Ghar Program?
The scheme is a subsidised housing finance program, officially called the Markup Subsidy and Risk Sharing Scheme for Affordable Housing Finance. Its goal is to help low and middle income families buy or build their first home. The government covers a large part of the markup, so borrowers get a low fixed rate for the first 10 years. It also boosts construction activity, which supports the wider economy.
Applications are submitted through the official Apna Ghar portal, and the loan itself is provided by the bank you select.
2. Key Features at a Glance
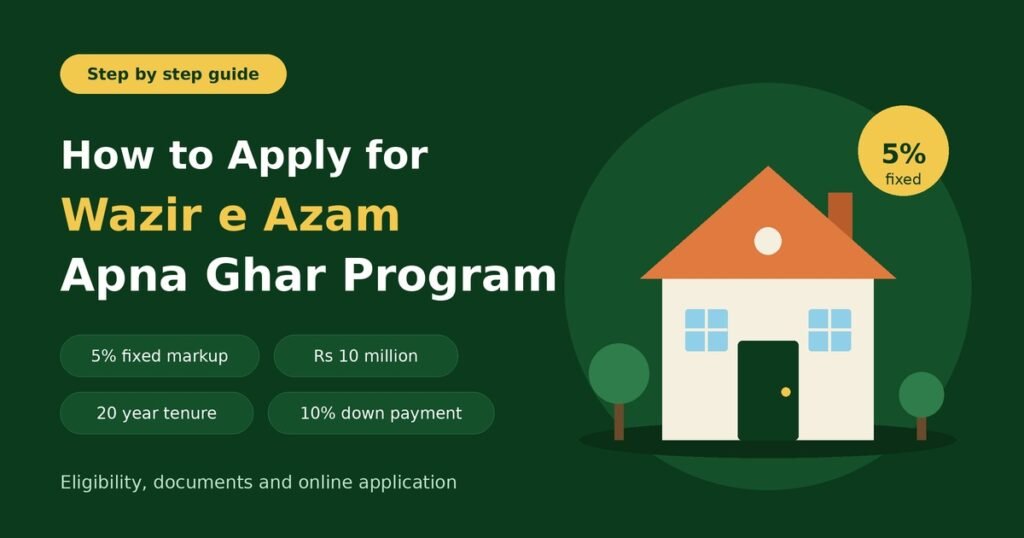
- Maximum financing: Rs 10 million
- Financing slabs: Rs 2.5 million, Rs 5 million, Rs 7.5 million and Rs 10 million
- Maximum loan tenure: 20 years
- Markup rate: 5% fixed for the first 10 years
- After year 10: the normal market rate applies, usually 1 year KIBOR plus 3%
- Down payment: at least 10%, with the bank financing the remaining 90%
- Processing fee: none
- Early repayment penalty: none
Banks may charge actual legal and valuation costs, as with any property loan, and some details can differ slightly from bank to bank.
3. What Can the Loan Be Used For?
The scheme covers three purposes:
- Buying a ready made house or flat
- Building a house on a plot you already own
- Buying a plot and building a house on it
There are size limits too. A house can be up to 10 marla (about 2,720 square feet), and a flat or apartment can be up to 1,500 square feet.
4. Who Can Apply? Eligibility Criteria
Please check these conditions before you apply:
- You must be a Pakistani citizen with a valid CNIC.
- You must be a first time homeowner, which means you do not already own a house, flat or other housing unit in your name.
- You should not have already benefited from another housing scheme.
- Salaried people, business owners, freelancers and people with informal income can all apply.
- Some banks require a minimum monthly net disposable income of Rs 37,000.
- The usual age range is 25 to 60 years. For salaried applicants, age at the end of the loan should not exceed 60, and for self employed applicants it should not exceed 65.
- Overseas Pakistanis with a NICOP or POC can also apply, with an age limit of up to 65 years.
Income and age rules can vary slightly between banks, so confirm them with your chosen bank before applying.
5. How the Down Payment Works
You need to arrange at least 10% of the property cost yourself. For example, if you apply for Rs 5 million, you must provide Rs 500,000 and the bank finances the remaining Rs 4.5 million.
You can pay more than 10% if you wish. A larger down payment means a smaller loan and a lower monthly installment. The online form lets you enter a higher equity percentage, such as 30%.
6. Which Banks Offer the Scheme?
The scheme includes commercial banks, Islamic banks, microfinance banks and the House Building Finance Corporation (HBFC). You choose your preferred bank during the application. If you prefer interest free financing, Islamic banks offer the scheme under Shariah compliant structures.
7. Documents Required
You will generally need the following:
- Clear copy of your CNIC, front and back
- A recent photograph
- Employment certificate (for salaried applicants)
- Salary slip
- Six months of bank statements
- Account maintenance certificate
- CNIC of your next of kin
- Documents of your co applicant, if you have one
- Property documents or details, if the bank asks for them
Important: the account maintenance certificate and the six month bank statement are two separate documents, and you must get both from your bank. All files should be clear and readable, in PDF or JPG format if the portal allows it.
8. How to Apply Online: Step by Step
Step 1: Open the portal. Go to apnaghar.gov.pk in your browser.
Step 2: Create an account. Click Create Account and enter your name, CNIC number, mobile number, email address and a password. Then click Register.
Step 3: Log in. Sign in with your CNIC and password, type the security code shown on the screen and click Sign In. Read the instructions on the portal, then click Apply Now.
Step 4: Select your applicant category. Choose Salaried Person if you earn a monthly salary, Business Income if you run a business, or the informal or other income option if you earn through freelancing or another non salary source. Pick carefully, because the rest of the form depends on this choice.
Step 5: Enter bank details. Select the bank you want the loan from, then enter the branch name and city. If you already have an account there, add the account details. Salaried applicants should preferably use the account where their salary is paid. Enter the normal account number, not the IBAN, if the portal asks for a simple account number. Click Save and Next.
Step 6: Choose the purpose of financing. Select one of the three options: buying a house or flat, buying a plot and building a house, or building on a plot you own. Then enter the amount you want to borrow.
Step 7: Add your equity contribution. Enter at least 10%, or more if you like. Then enter the city where the property is located and choose your loan tenure, up to 20 years. Click Save and Next.
Step 8: Fill in personal details. You will enter your CNIC issue date, date of birth, mobile number, gender, father’s name and CNIC number, marital status, number of dependents and mother’s name. You will also select your residence status, such as own house, rented house, rented apartment, hostel or living with family. If you pay rent, enter the monthly amount. Then add your province, district, residential address and mailing address, which can be the same.
Step 9: Add a co applicant, if any. If you are applying together with a spouse, sibling or another eligible family member, select Yes and enter their name, relationship, CNIC number, mobile number, email and monthly income. If you are applying alone, select No.
Step 10: Add guarantor details and photo. A guarantor can be a close relative, friend or another suitable person. You may need to provide their name, CNIC number and income details. Then upload your photograph and click Save and Next.
Step 11: Enter employment details. Salaried applicants should enter employer name, job type, office address, designation, joining date, net monthly income and office phone number. Always enter net income, meaning the amount you receive after tax and deductions, not your gross salary. The bank may call the office number to verify your job, so make sure it is correct. Add previous employer details only where the form requires them.
Step 12: Upload documents. Upload all the documents listed above and check that every file is clear.
Step 13: Submit your application. Review the whole form carefully, tick the confirmation box and click Submit Application. Your application then goes to the bank for processing.
9. Tips to Make Your Application Stronger
- Enter all details exactly as they appear on your CNIC and bank records.
- Report your net income correctly and use your salary account.
- Scan documents clearly, because blurry or incomplete files can delay processing.
- Use a mobile number and email address you check daily, since the bank will contact you there.
- Estimate your monthly installment in advance and make sure it fits comfortably in your budget.
- If possible, pay more than the minimum 10%, which reduces your loan and your installment.
10. Important Precautions
- Do not pay anyone in advance. The scheme has no processing fee, so anyone asking for money to “approve” your loan may be a fraudster.
- The rate changes after 10 years. From year 11 the market rate applies, so plan a budget that you can still manage at that point.
- First home only. If you already own a house in your name, you are not eligible.
- Rules can change. Banks and the government may update the terms, so check the official portal and your bank before applying.
11. Frequently Asked Questions
Is there a processing fee?
No, the scheme has no processing fee.
Is there a penalty for repaying early?
No, there is no prepayment penalty.
How long can the loan last?
Up to 20 years, with the fixed 5% rate applying for the first 10 years.
Can freelancers and informal income earners apply?
Yes. The scheme is open to salaried, business, freelance and informal income earners, as long as they meet the bank’s income requirements.
Can two people apply together?
Yes, you can add a co applicant such as a spouse, brother or another eligible relative.
Is there an Islamic banking option?
Yes, Islamic banks participate in the scheme.
What if I already own a house?
You cannot apply, because the scheme is only for first time homeowners.
Final Thoughts
The Ghar Ho Tu Apna scheme gives many families a real chance to own a home. A low fixed rate, a 10% down payment, no processing fee and up to 20 years to repay make it far more accessible than a regular loan. If you meet the requirements, keep your documents ready and apply online as soon as you can.